How to Sell a House in Houston When the Buyer’s Financing Keeps Falling Through
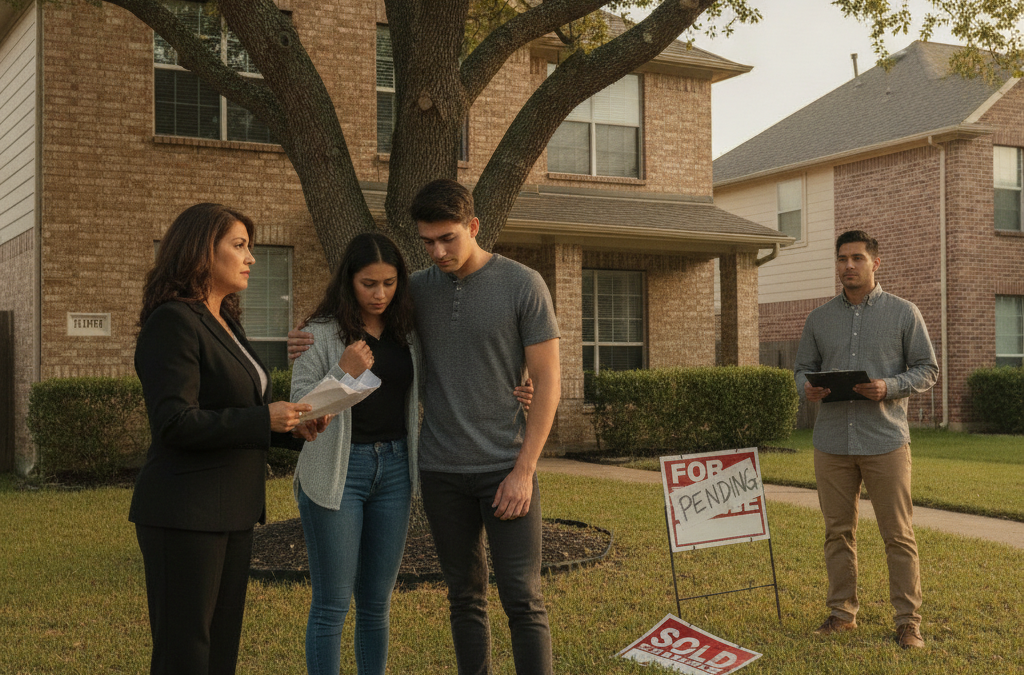
When a home sale falls apart because a buyer couldn’t get their mortgage approved, it isn’t just frustrating — it can derail your entire timeline. In Houston’s real estate market, financing failures happen more often than most sellers expect, and they hit hardest when you’re already under pressure: carrying two mortgages, relocating for work, or trying to move forward after a major life change. If this has happened to you once — or more than once — you’re not alone, and there’s a straightforward path out of the cycle.
Why Buyer Financing Falls Apart So Frequently in Houston
Houston’s housing market is large, geographically spread out, and highly variable in price. A buyer who qualifies for a home in Pearland on paper might not qualify for a comparable property in a neighborhood closer to the 610 Loop, simply because appraisals and loan limits interact differently based on location. Add in the volatility of Houston’s energy-sector employment base — where income can shift significantly from one quarter to the next — and you have a buyer pool that lenders scrutinize closely.
Financing deals also collapse for reasons that have nothing to do with the buyer’s intent. Common causes include:
- Low appraisals — The lender’s appraiser values the home below the agreed purchase price, forcing a renegotiation or loan denial.
- Last-minute credit changes — A buyer opens a new credit account, changes jobs, or takes on new debt between signing and closing.
- Income verification problems — Freelancers, contract workers, and energy-sector employees paid through variable structures often struggle to document income to a lender’s satisfaction.
- Debt-to-income ratio issues — Rising interest rates in recent years have pushed many buyers to the edge of what they qualify for, and a small change can push them over the line.
- Property condition flags — If your home has deferred maintenance, older systems, or flood history, lenders may refuse to approve the loan without repairs being made first.
That last point is especially relevant in Harris County and the surrounding Gulf Coast region. Properties with any history of flooding — even disclosed, remediated flooding — can trigger heightened scrutiny from lenders. If your home has ever taken on water, getting a conventional buyer to the finish line can be genuinely difficult, even when the buyer wants to close.
What Happens When a Deal Falls Through: The Hidden Cost to Sellers
Most sellers focus on the emotional toll of a collapsed deal. But the financial cost is real and often underestimated. When a buyer’s financing falls through, you typically lose:
- Weeks or months off your timeline — time the property sat under contract and off the market
- Carrying costs you kept paying: mortgage, taxes, insurance, and utilities
- Momentum with other potential buyers who may have moved on
- Negotiating position, especially if you relist and buyers notice the days-on-market count
In some cases, you may also owe a price reduction on the relist, because a home that’s been under contract and returned to the market often raises questions. Buyers wonder what went wrong, even when the answer has nothing to do with the property itself.
If you’re selling a home in Katy, Sugar Land, or Baytown and you’re already stretched thin — maybe you’ve already moved out, or you’re paying rent somewhere else while the house sits — every week of delay has a dollar figure attached to it.
The Gap Most Competitors Don’t Address: Repeat Financing Failures
Here’s something worth saying plainly: most advice for sellers whose deals fall through is just “relist and try again.” That’s the standard guidance, and for a seller with time and financial cushion, it may be fine. But if you’ve already been through this once — or twice — and you’re facing a deadline, relisting on the MLS is not a solution. It’s a repeat of the same problem.
What you actually need is a buyer who doesn’t depend on a lender’s approval. That’s the core value of a cash sale. When a cash buyer makes you an offer, there is no financing contingency. There is no appraisal required by a bank. There is no underwriter reviewing your property’s flood disclosure history. The offer is what it is, and if you accept it, the path to closing is direct.
At Hero Homebuyers Houston, the process is simple: you request a cash offer, we schedule a walkthrough, and you choose the closing date that works for you — often within seven to fourteen days. You don’t need to make repairs, clean the property, or pay a commission. See exactly how the process works here.
Is a Cash Offer Always Lower? What Sellers in Houston Should Actually Expect
This is the question most sellers have, and it deserves a straight answer. Cash offers from buyers like Hero Homebuyers are typically below full retail market value — that’s honest. What they replace, though, is a meaningful set of costs and risks that a traditional sale carries.
Consider what you’re not paying in a cash sale: no agent commissions (typically 5–6% in Houston), no closing costs shifted back to you through negotiation, no repair requests following inspection, no price reduction after a low appraisal, and no months of carrying costs while you wait for a qualified buyer to materialize. When you add those numbers up, the gap between a cash offer and a financed offer often narrows considerably.
More importantly: a cash offer that closes is worth far more than a financed offer that doesn’t. If your last deal fell apart at the finish line after sixty days under contract, you understand this intuitively.
When a Cash Sale Makes the Most Sense After a Financing Failure
Not every seller needs to go the cash route after one failed deal. But if any of the following apply to you, it’s worth taking seriously:
- You’ve had one or more deals collapse due to financing, appraisal, or inspection issues
- Your home has deferred maintenance, flood history, or condition issues that make lender approval difficult
- You’re carrying two properties at once and the financial drain is real
- You have a hard deadline — a job start date, a divorce settlement, a court order — that won’t wait for another six-week escrow cycle
- You’ve already moved out and the property is vacant, which introduces its own carrying costs and liability
If you’re in the greater Houston area — whether you’re in Harris County proper, out in Fort Bend County, or in a suburb like Pearland or Katy — selling fast for cash is a realistic option that many local homeowners use specifically to escape the financing contingency cycle.
Frequently Asked Questions
Can I accept a cash offer even if my home is already listed with an agent?
Yes, but you’ll want to check your listing agreement for exclusivity terms. Some agreements allow you to sell to a buyer you source independently; others require commission payment regardless. Review the terms with your agent or an attorney before proceeding.
What if the cash offer comes in significantly lower than what my financed buyer offered?
That’s a real trade-off to weigh. A useful exercise is to subtract agent commissions, estimated repair requests, carrying costs during a new listing period, and the risk of another financing failure from your financed offer — then compare that adjusted number to the net cash offer. Many sellers find the gap is smaller than it first appears.
Does a cash buyer still do an inspection?
A reputable cash buyer will typically do a walkthrough to assess the property’s condition, but they’re not buying on behalf of a lender. There’s no lender-mandated appraisal, no required repairs, and no third-party underwriter who can kill the deal at the last minute. The walkthrough informs the offer — it doesn’t create new contingencies after the fact.
How quickly can Hero Homebuyers actually close in Houston?
In most cases, we can close in as little as seven days if the title is clear and you’re ready to move. If you need more time — to arrange your move, line up your next home, or coordinate with other parties — we can work around your schedule. The closing date is yours to choose.
What if my home has flood history — will that affect a cash offer?
Flood history is a complicating factor for financed buyers because lenders are cautious about properties with prior water damage. A cash buyer doesn’t have that lender filter. We buy homes as-is in the Houston area, including properties with disclosed flood history, and we’ll give you a straightforward offer based on the property’s actual condition.
Stop the Cycle — Get a Straightforward Cash Offer
If you’ve been through the frustration of a deal falling apart over financing — especially more than once — you don’t have to keep rolling the dice with buyers who need mortgage approval. Hero Homebuyers Houston works with homeowners across the greater Houston area, from Harris County neighborhoods to suburbs like Katy, Baytown, Sugar Land, and Pearland, offering a simple, honest cash sale process with no repairs, no commissions, and no financing contingencies to worry about.
When you’re ready to stop waiting and start closing, request your free, no-obligation cash offer here. There’s no pressure, no fees, and no obligation to accept. Just a real offer from a locally operated Houston home buyer who understands what you’re dealing with.