How to Sell a Flood-Damaged House in Houston Without Waiting on Insurance or FEMA
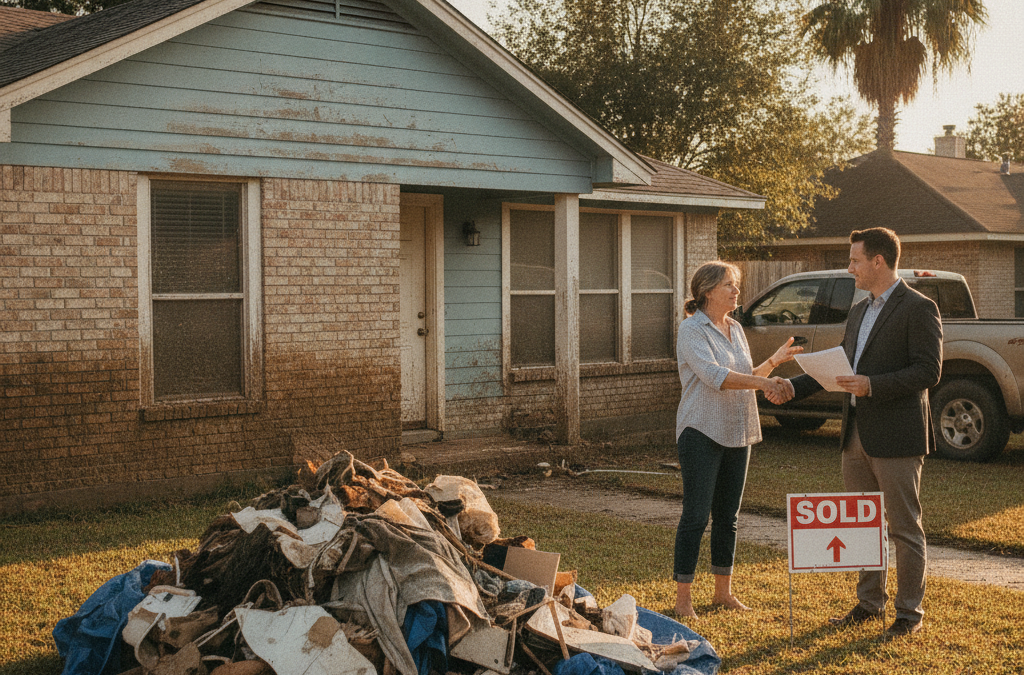
Yes — you can sell your flood-damaged Houston home right now, without completing repairs, without waiting months for an insurance settlement, and without going through a FEMA appeals process that may leave you with far less than you expected. If your house flooded and you’re done waiting, a cash sale is often the fastest and most straightforward exit available to you.
Greater Houston has flooded repeatedly over the past decade — Harvey, Imelda, and countless unnamed rain events have left tens of thousands of homes in Harris County, Fort Bend County, Brazoria County, and Galveston County with water damage ranging from minor to catastrophic. For many homeowners, the aftermath isn’t just wet drywall. It’s months of uncertainty, underpaid claims, mold remediation bills, and a house that won’t sell on the open market because no traditional buyer’s lender will finance it in that condition.
This article is for you if you’re in that situation — and you want to understand exactly what your options are.
Why the Insurance and FEMA Route Often Leaves Houston Homeowners Stuck
It’s worth being honest about why so many flooded homeowners in Houston find themselves in a holding pattern long after the water recedes.
National flood insurance payouts through FEMA’s NFIP program are capped and frequently disputed. Adjusters are stretched thin after major storm events, timelines stretch out, and many homeowners discover their payout doesn’t come close to covering the actual cost of making the house livable again — let alone sellable. Private flood insurance claims aren’t always faster. And if you didn’t carry flood insurance at all (a surprisingly common situation in areas that weren’t mapped as high-risk prior to Harvey), you may be looking at FEMA individual assistance grants that typically max out well below the actual damage costs.
Meanwhile, the house sits. Mold spreads. The structure deteriorates. Property taxes keep coming. And if you’re paying rent or a mortgage somewhere else while the flooded house sits empty, every month of waiting costs you real money.
What Selling As-Is Actually Means for a Flood-Damaged Home
When a cash home buyer says they purchase flood-damaged houses as-is, they mean it literally. You don’t need to:
- Gut and remediate the drywall or flooring
- Pass a home inspection
- Get the property out of a flood zone designation
- Resolve an open insurance claim before closing
- Clean, stage, or show the property to anyone
- Pay a realtor commission or closing costs out of pocket
A legitimate local cash buyer walks through the property, assesses the damage honestly, and makes you a straightforward offer based on what the house is worth in its current condition — accounting for the flood damage, the cost of remediation, and the after-repair value in your specific neighborhood. There are no financing contingencies to worry about. No bank appraiser who refuses to sign off on a flood-damaged structure. No buyer who backs out during inspection because they got scared of the scope of work.
You choose the closing date. If you need two weeks, fine. If you need 30 days to sort out logistics, also fine. The point is that you’re in control of the timeline — not the insurance company, not a lender, not a buyer’s cold feet.
The Part Competitors Aren’t Telling You: What Happens to Your Insurance Claim When You Sell
Here’s a detail that most cash buyer websites — including most of the ones you’ve probably already read — completely skip over. And it matters.
If you have an open or pending flood insurance claim when you sell, that claim typically transfers with the policy or gets resolved at closing depending on how it’s structured. In many cases, you can assign the claim proceeds to the buyer as part of the negotiation — meaning the buyer takes on the property and the responsibility of completing the claim, and you walk away without having to manage that process. In other cases, you may need to close out or formally withdraw the claim before the title can transfer cleanly.
This is not a reason to avoid selling — it’s a reason to work with a buyer who has done this before and knows how to navigate it. A locally operated buyer who has purchased flood-damaged homes in Harris County, Pearland, Humble, and Baytown will understand the paperwork involved and won’t leave you hanging at the closing table over a claim technicality. An out-of-state investor franchise almost certainly won’t.
Before you accept any cash offer on a flood-damaged home, ask the buyer directly: Have you purchased homes with open flood insurance claims before? How did you handle it? Their answer will tell you a lot about whether they actually know what they’re doing in this market.
Flood Zone Designation and Disclosure: What You’re Required to Do in Texas
Texas law requires sellers to disclose known flooding history and flood zone status to potential buyers. This applies whether you’re selling to a cash buyer or listing on the MLS. A reputable cash buyer already expects this and won’t penalize you for disclosing it — they’ve built it into their offer. The disclosure requirement is not a barrier to selling; it’s just part of the process.
If your home is in a FEMA-designated Special Flood Hazard Area (100-year floodplain), that affects the buyer’s future insurance costs but doesn’t prevent a cash sale. And if your home has flooded multiple times — which applies to a significant number of properties along Houston’s bayou corridors and in low-lying areas of Katy, Missouri City, and similar communities — that’s relevant information, but again, not a deal-breaker for a cash buyer who specializes in distressed properties.
How the Process Works When You Sell to Hero Homebuyers
The process is designed to be simple, especially when you’re already dealing with enough. Here’s how it works: you reach out and share some basic details about your property, we schedule a walkthrough at your convenience, and we make you a no-obligation cash offer. If it works for you, we move forward on your timeline. If it doesn’t, there’s no pressure and no cost to you.
We buy flood-damaged homes throughout greater Houston — including properties in Harris County flood zones, homes that took on water during Harvey and never fully recovered, and houses that have been sitting vacant and deteriorating since the last storm event. You don’t need to clean anything out, make any repairs, or coordinate with your insurance adjuster before reaching out to us.
Frequently Asked Questions
Can I sell my Houston home if it’s still in the middle of an active flood insurance claim?
In many cases, yes. How the open claim is handled at closing depends on how your policy is structured and how the purchase agreement is written. An experienced local cash buyer can walk you through your specific situation. Don’t assume an open claim automatically blocks a sale — it often doesn’t.
Do I have to disclose flooding history when selling to a cash buyer in Texas?
Yes. Texas law requires sellers to disclose known flooding history on the seller’s disclosure form, regardless of who the buyer is. A cash buyer who works in this market expects this and will already factor it into their offer. Disclosure protects you legally — it’s not something to try to work around.
Will I get a fair price for a flood-damaged house, or are cash buyers just lowballing?
A legitimate local buyer makes an offer based on the real after-repair value of your home in your specific neighborhood — not a formula designed to exploit your situation. You’re not going to get full retail value on a damaged home; no buyer of any kind will pay that. But a fair offer accounts for what your home is genuinely worth given its condition, and you save on repairs, realtor commissions, holding costs, and months of uncertainty that would otherwise eat into a traditional sale anyway.
What if my flood-damaged home also has mold? Will that prevent a sale?
No. Mold is one of the most common outcomes of Houston flooding, and cash buyers who specialize in distressed properties purchase homes with active mold issues regularly. You don’t need to remediate before selling. The condition is factored into the offer.
How fast can I actually close on a flood-damaged house in Houston?
Closings can happen in as little as seven days once you’ve accepted an offer and title work is underway. If you need more time to make arrangements, the closing date is flexible. The timeline is yours to set — not the buyer’s.
Ready to Move Forward? Let’s Talk.
If your Houston-area home flooded and you’re tired of waiting — on insurance adjusters, on FEMA, on a market that doesn’t want to touch a damaged property — there’s a straightforward option available to you right now. Hero Homebuyers Houston works with homeowners across Harris County and the surrounding region who need to sell flood-damaged, storm-damaged, or otherwise distressed properties without the usual hassle.
You don’t have to finish the repairs. You don’t have to wait for a settlement. You just have to decide you’re ready to move on. Request your free, no-obligation cash offer today and find out what your home is worth as-is — with no pressure, no fees, and no strings attached.