How to Sell a Flood-Damaged House in Houston Without Waiting on Insurance or Making Repairs
Yes — you can sell a flood-damaged house in Houston as-is, without waiting for an insurance payout, without hiring a single contractor, and without listing it on the MLS and hoping a buyer’s lender doesn’t walk away at inspection. If your home has taken on water — whether from a named storm, a bayou overflow, a burst pipe, or repeated street flooding — you have more options than most people realize. And one of those options can put cash in your hand in as little as seven days.
This guide walks you through exactly what that looks like, what to watch out for, and why so many Houston homeowners in your situation choose to skip the repair-and-list route entirely.
Why Flood Damage Makes a Traditional Sale So Complicated in Houston
Houston’s relationship with flooding is not a secret. From Hurricane Harvey’s historic 2017 devastation to the repeated Tax Day floods, Memorial Day floods, and the ongoing drainage struggles across Harris County, Galveston County, Brazoria County, and Fort Bend County — water damage is one of the most common reasons Houston homeowners find themselves in a tough spot when trying to sell.
The problem is that traditional real estate sales — listing with an agent, staging, open houses, buyer financing — all fall apart quickly when flood damage is in the picture:
- Mortgage lenders won’t finance flood-damaged homes until repairs meet specific standards. Most conventional buyers need a loan, so your buyer pool shrinks dramatically.
- Inspections expose everything. Even partially remediated flood damage triggers red flags for buyers and their inspectors, often killing deals late in the process.
- Flood disclosure requirements in Texas are real. You’re legally required to disclose known flooding history, which further limits buyer interest on the open market.
- Insurance timelines stretch for months. If you’re waiting on a FEMA claim, a private flood policy payout, or a dispute with your adjuster, you could be stuck in limbo — still paying the mortgage, still paying taxes, still watching the mold spread.
- Repair costs are brutal. Drywall, flooring, subfloor, electrical, HVAC, mold remediation — a moderate flood event can easily push $40,000 to $80,000 in repairs before you’re even back to baseline.
If any of this sounds familiar, you’re not alone. And you don’t have to grind through all of it just to sell your house.
What “Selling As-Is” Actually Means for a Flood-Damaged Home
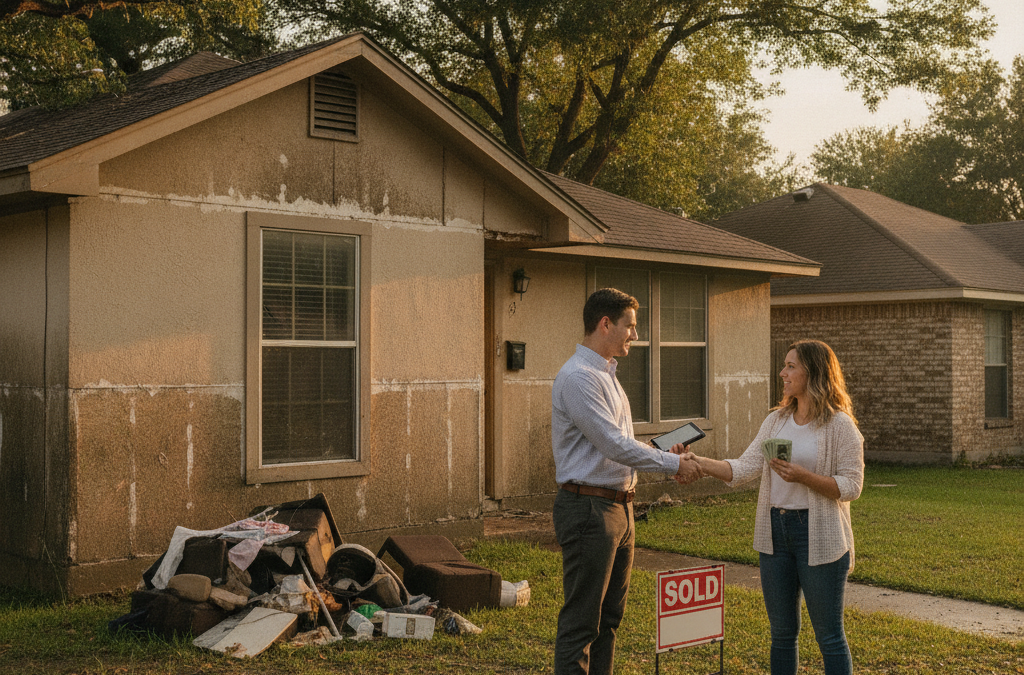
When a cash buyer like Hero Homebuyers Houston says we’ll buy your home as-is, that’s not a marketing line with an asterisk. It means we walk through the property in its current condition — water-stained walls, buckled floors, gutted drywall, musty smell and all — and we make you an offer based on what the home is worth as it sits today, not what it might be worth after a full renovation.
You don’t clean it up. You don’t hire a remediation crew first. You don’t get three contractor bids and try to manage a construction timeline from across town or out of state. You just tell us about the property, we schedule a walkthrough, and we bring you a no-obligation cash offer. Here’s exactly how the process works if you want to see it laid out step by step.
There are no realtor commissions taken out of your proceeds. No closing costs passed back to you. You pick the closing date — whether that’s 10 days from now or six weeks from now while you figure out where you’re moving.
The Insurance Trap: Why Waiting on a Payout Isn’t Always the Right Move
This is the section most competitor websites skip entirely — and it’s one of the most important decisions you’ll face after a flood.
A lot of homeowners assume the right move is to file the insurance claim, wait for the settlement, use the money to repair the house, and then sell it at full market value. In theory, that makes sense. In practice, it’s often a six-to-twelve month ordeal that costs more in stress, mortgage payments, and carrying costs than the insurance check is worth.
Here’s what actually happens in many Houston flood cases:
- The initial claim offer from FEMA or your private insurer comes in lower than actual repair costs — sometimes significantly lower.
- You dispute it, hire a public adjuster, wait for a re-inspection, and negotiate. Months pass.
- Meanwhile, mold continues to spread. Secondary damage worsens. Your homeowner’s insurance may not cover what the flood policy missed.
- Contractors in high-demand post-storm periods are booked out, charging premium rates.
- After repairs, you still have to disclose the flooding history to buyers — and that affects market value regardless of how nice the renovation looks.
For some homeowners, especially those in areas like Humble, Pearland, or Baytown that flood repeatedly, the math simply doesn’t add up. The repaired home will sell — but after a year of carrying costs and construction headaches, the net proceeds may be no better than a fair cash offer today.
That doesn’t mean taking an insurance check is always wrong. But it’s worth running the real numbers before you assume the repair-and-list path is the smarter play.
Can You Accept an Insurance Settlement and Still Sell to a Cash Buyer?
Yes — in most cases. If you’ve already received a partial payout or a remediation check, that money is generally yours regardless of how you sell the property, as long as you haven’t already contracted repairs. If you’re still mid-claim, a real estate attorney or title company can help you understand how the sale interacts with your open claim. This is common in Harris County and surrounding areas, and an experienced local cash buyer will have navigated this before.
What you typically cannot do is double-collect — accept an insurance payout for repairs and then sell the home without completing those repairs without disclosing the situation. Transparency matters here both legally and practically.
What About Homes in a Flood Zone or with a History of Repeated Flooding?
Texas law (specifically Senate Bill 339, passed after Harvey) requires sellers to disclose whether a home has flooded before — and how many times. If your property is in a FEMA-designated flood zone, is subject to mandatory flood insurance requirements, or has flooded more than once, you must disclose that to any buyer.
For traditional buyers using financing, repeated flood history is often a deal-killer. For cash buyers, it’s a factor in pricing — but it doesn’t stop the sale. Homeowners throughout the Greater Houston area sell flood-zone properties to us regularly, including homes along bayou corridors, near Brays Bayou, Greens Bayou, and in low-lying neighborhoods from League City up through the northern Harris County communities.
The 3-Step Process for Selling Your Flood-Damaged Houston Home
We keep it straightforward because you’re already dealing with enough:
- Step 1 — Request your offer. Call us or fill out the short form online. Tell us about the property and the damage. No need to have all the answers — we’ll ask the right questions.
- Step 2 — Schedule a walkthrough. We visit the property as-is. No staging, no cleaning, no repairs needed beforehand. We assess what we’re working with and prepare a fair, no-obligation cash offer.
- Step 3 — Close on your timeline. If you accept, we move to closing. We handle the title work. You pick the date. We can close in as little as 7 days, or we can work around your schedule if you need more time.
No commissions. No fees. No financing contingencies that fall apart at the last minute.
Frequently Asked Questions: Selling a Flood-Damaged Home in Houston
Do I have to finish mold remediation before selling to a cash buyer?
No. We buy homes with active mold issues, incomplete remediation, and unaddressed water damage. You don’t need to spend a dollar on remediation before we make you an offer. We factor the condition into our assessment.
What if my house is still in a FEMA-declared disaster area?
You can still sell. FEMA disaster declarations don’t prevent property sales. In fact, selling quickly can be one of the fastest ways to stop the financial bleeding if you can’t afford to wait for federal assistance to trickle through. We’re familiar with the process across Harris County and surrounding Gulf Coast communities.
Will you buy a house that has flooded multiple times?
Yes. Repeated flood history affects pricing, but it doesn’t disqualify a property. Many homes in Humble, Baytown, and parts of unincorporated Harris County have flooded more than once, and their owners still have options. We’ll give you an honest offer based on the real picture.
What if I still have a mortgage on the flood-damaged home?
That’s fine and very common. The cash proceeds from the sale go toward paying off your remaining mortgage balance at closing, and you receive the difference. If you owe more than the home is currently worth in its damaged state, we can discuss short sale options or help you think through next steps — we’ll be straight with you about what makes sense.
How is your cash offer calculated for a damaged home?
We look at the home’s location, its after-repair value (what it would be worth fully restored), the estimated cost and scope of repairs, and current market conditions in your specific neighborhood. We don’t use a blanket formula — a flooded bungalow in League City is a different situation than a flooded home in Midtown Houston, and we treat it that way.
Ready to Stop Waiting and Move Forward?
If your Houston-area home has flood damage and you’re tired of managing insurance calls, contractor bids, and an uncertain sale timeline, we’re here to make this simple. Hero Homebuyers Houston buys flood-damaged homes throughout Harris County and the surrounding region — as-is, fast, for cash, with no fees taken from your proceeds.
You don’t have to have it all figured out before you call us. Request your free, no-obligation cash offer today and find out exactly where you stand — no pressure, no obligation, just a straight answer from a local team that knows this market.