How to Sell a Flood-Damaged House in Houston Without Waiting on Insurance or FEMA
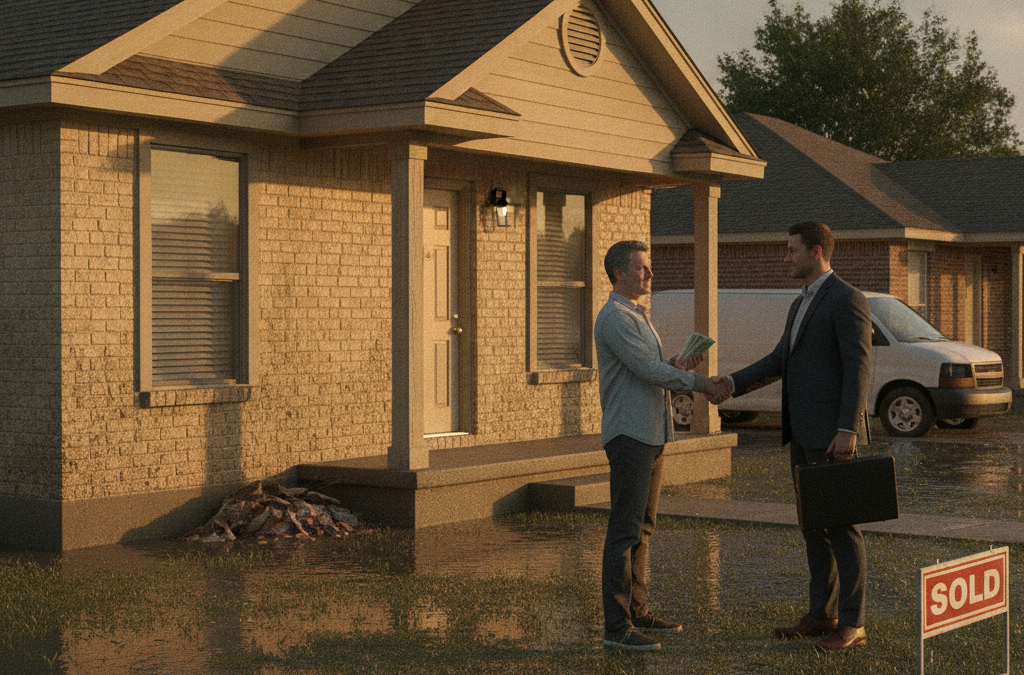
Yes — you can sell your flood-damaged home in Houston without waiting for an insurance settlement to close, without completing a single repair, and without spending another month paying mortgage and utilities on a house you can no longer live in. If a storm, hurricane, or flooding event has damaged your property, a direct cash sale may be the fastest and most straightforward path forward. This guide walks you through exactly how that works, what to watch out for, and why so many Houston-area homeowners are choosing this route over the long, uncertain road of insurance claims and contractor timelines.
Why Flood-Damaged Homes Are Such a Complicated Sell in Houston
Houston sits in one of the most flood-prone metro areas in the country. The Gulf Coast geography, combined with the region’s flat terrain, clay-heavy soil, and rapid urban development, means that flooding isn’t a rare catastrophe here — it’s a recurring reality for tens of thousands of homeowners across Harris County, Galveston County, Brazoria County, and beyond. Events like Harvey in 2017 put this reality into sharp focus, but smaller, damaging floods happen along the I-10 and I-45 corridors every few years.
When your home floods, the traditional selling process becomes a serious obstacle course:
- Most retail buyers require financing, and lenders won’t approve a mortgage on a home with active water damage or unresolved flood claims
- Required disclosures about prior flooding can spook buyers and trigger lowball offers
- Remediation and rebuild timelines can stretch 6 to 18 months — time you may not have
- Insurance adjusters are often backed up after major storm events, adding months to an already slow process
- FEMA assistance, while helpful, rarely covers the full scope of repairs — and it comes with its own delays and paperwork
The result: you’re stuck in limbo, making payments on a house you can’t sell, can’t fully repair, and in some cases can’t safely live in.
What Most Competitors Don’t Tell You: You Don’t Have to Wait
Here’s the part that most cash buyer websites gloss over: the insurance claim and the sale are separate transactions. You are not legally required to repair your home before selling it. You are not required to wait for a FEMA determination. And in many cases, you can assign or retain your insurance claim proceeds independently of the sale — though you’ll want to verify the specifics with your insurer and a real estate attorney before closing.
What this means in practice is that as soon as you decide you want out, you can begin the process of requesting a cash offer. A legitimate local buyer — one who actually knows the Houston market and has dealt with post-storm properties in Humble, Katy, Pearland, and Cypress — will factor the home’s current as-is condition into their offer. No waiting on remediation. No competing contractor bids. No permit pulls.
If you’re curious how the process works from start to finish, here’s a straightforward breakdown of what to expect when you work with Hero Homebuyers Houston.
How a Cash Sale Works for a Flood-Damaged Home
The process is simpler than most homeowners expect, especially compared to the traditional listing route:
- Step 1 — Request your offer. You share basic information about your property. There’s no obligation, no pushy follow-up, and no cost to you.
- Step 2 — We walk through the property. A local buyer will schedule a walkthrough — not an inspector hired to find reasons to cut the offer, but someone who genuinely understands what flood-damaged homes in the Houston area look like and what they’re worth in their current state.
- Step 3 — You choose your closing date. Once you accept an offer, you pick the timeline that works for you. Some homeowners close in as little as seven days. Others need a few weeks to sort out logistics. Either way, it’s your call.
There are no realtor commissions, no closing costs paid by you, no repair demands, and no financing contingencies that can fall through at the last minute. The offer you accept is the amount you walk away with.
What Happens to Your Insurance Claim If You Sell As-Is?
This is the question most homeowners ask first — and it’s the right one to ask. The short answer is: it depends on the structure of your claim and your policy, and you should absolutely consult with your insurance company and a Texas-licensed real estate attorney before signing anything.
Here’s the general framework:
- If your claim has already been paid out to you, those funds are generally yours and are not automatically tied to the property sale
- If your claim is still in process, your mortgage lender may have rights to a portion of the insurance proceeds — this is common with escrowed accounts
- If there is an active insurance check made out jointly to you and your lender, that will need to be resolved as part of the title and closing process
- FEMA grants are typically non-transferable and tied to your occupancy as a primary residence — again, confirm this with a local attorney
A reputable cash buyer should be upfront about all of this and give you time to sort it out before closing. If anyone is pressuring you to sign before you’ve had a chance to consult a professional, that’s a red flag.
Selling After a Flood in Suburban Houston: Pearland, Humble, Baytown, and Beyond
Flood risk doesn’t follow city limits. Some of the most flood-impacted communities in Greater Houston sit outside the 610 Loop — in areas like Pearland, Humble, Baytown, League City, Katy, and Cypress. These markets have a mix of older housing stock and newer subdivisions that were built in areas that have since been reclassified into flood zones, which complicates both insurance and resale.
If your home is in a Special Flood Hazard Area (SFHA) and has flooded more than once, it may also be subject to the NFIP’s Repetitive Loss program, which can further restrict your options or affect your insurance payout. Homeowners in these situations often find that a direct cash sale — even at a discount to market — is a better financial outcome than years of escalating flood insurance premiums, repeated repairs, and a home that becomes harder to sell every time it takes on water.
If you’re ready to explore your options, request a free, no-obligation cash offer here and find out what your home is worth in its current condition.
Frequently Asked Questions: Selling a Flood-Damaged Home in Houston
Do I have to disclose flooding history when I sell my house in Texas?
Yes. Texas law requires sellers to disclose known flooding, water intrusion, and related damage in the Seller’s Disclosure Notice. This applies whether you sell on the open market or to a cash buyer. A legitimate buyer already accounts for this in their offer — it won’t be a surprise that tanks the deal.
Can I sell my house while an insurance claim is still open?
In most cases, yes — but there are nuances depending on your lender and the structure of the claim. You should notify your insurer of the pending sale and consult a real estate attorney to make sure the claim is properly handled at closing. A good title company can often help coordinate this.
Will a cash buyer give me a fair offer on a flood-damaged home in Harris County?
A fair offer on a flood-damaged home reflects the home’s as-is condition, local comparable sales, and the cost of remediation and repairs a buyer will need to take on. It won’t equal full market value of a move-in-ready home — but it also won’t cost you months of holding costs, contractor headaches, or realtor commissions. The right buyer will be transparent about how they arrived at their number.
What if my home has already been gutted but not rebuilt?
That’s actually a common situation in Houston after major flood events — homeowners gut the drywall to prevent mold and then stall out waiting on funds or contractors. Cash buyers can still make offers on gutted, partially remediated homes. In some ways, a gutted interior gives a buyer a cleaner picture of the structural condition.
How fast can I actually close on a flood-damaged home?
Once an offer is accepted and title work is clear, closings can happen in as few as seven days. If there are outstanding insurance liens or lender holds on insurance proceeds, that timeline may extend slightly — but it’s almost always faster than the traditional listing route, which can take three to six months even for move-in-ready homes in a normal market.
You’ve Been Through Enough — Let’s Make the Next Step Simple
Dealing with flood damage is exhausting. Between the insurance calls, the FEMA paperwork, the mold concerns, the displaced living situation, and the financial pressure, the last thing you need is a complicated home sale on top of it. If you’re ready to stop waiting and start moving forward, Hero Homebuyers Houston is here to give you a straight answer and a fair cash offer — on your timeline, with no pressure.
We buy flood-damaged, storm-damaged, and water-damaged homes across Houston and surrounding Harris County communities, including Pearland, Humble, Baytown, Katy, Cypress, and League City. No repairs. No cleaning. No realtor fees. Just a simple process and a closing date you choose.
Contact us today to get started — or request your free cash offer online in just a few minutes. There’s no obligation, and you’ll have a real number to work with so you can make the best decision for your family.